Two investors buy the same bond on the same day. One pays ₹9,500; the other pays ₹10,500. Each receives the same ₹800 annual coupon and the same ₹10,000 principal repayment after three years, assuming the issuer pays as promised.
Would they earn the same return? Clearly not. One paid ₹1,000 more for the identical stream of money.
This is why a coupon alone cannot answer the question, “What will I earn?” It describes one part of the contract. Your return also depends on the price, timing, costs, taxes and actual outcome.
Start with the coupon
In our recurring hypothetical example, the face value is ₹10,000 and the annual coupon rate is 8%. With principal unchanged, annual interest is ₹10,000 × 8% = ₹800.
The issuer does not recalculate that fixed coupon using your secondary-market purchase price. Paying more or less for the instrument changes your economics, not this contractual calculation. The exception would be a change required by the instrument’s own terms; we are discussing a plain fixed-rate example here.
Current yield answers a smaller question
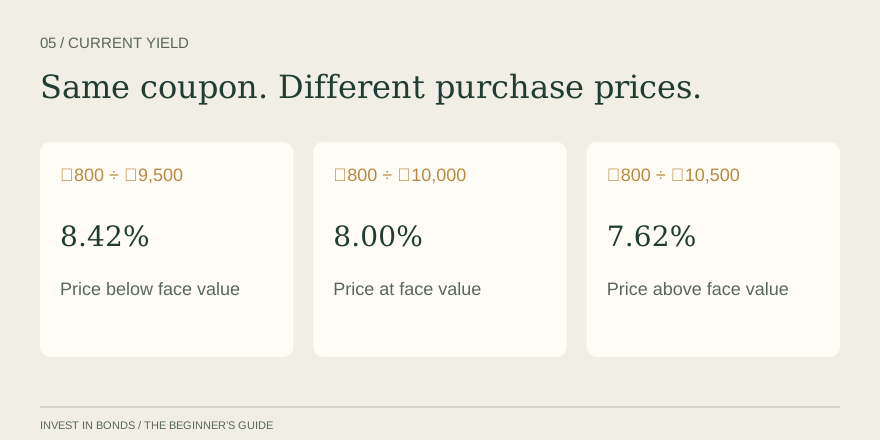
Current yield divides annual coupon income by the bond’s price. It is a quick income-to-price comparison, with the price basis needing to be clear. In our simplified example, purchases happen exactly one year before the next coupon, with three full annual periods remaining and no accrued interest or charges.
| Purchase price | Annual coupon | Current yield | Principal due at maturity |
|---|---|---|---|
| ₹9,500 | ₹800 | 8.42% | ₹10,000 |
| ₹10,000 | ₹800 | 8.00% | ₹10,000 |
| ₹10,500 | ₹800 | 7.62% | ₹10,000 |
These calculations are simply ₹800 divided by each price. They leave out the difference between the purchase price and the ₹10,000 redemption amount. That is why they do not describe the full return to maturity.
The buyer paying ₹9,500 has a potential ₹500 gain on principal repayment. The buyer paying ₹10,500 has a ₹500 difference to absorb. Both statements assume full repayment and ignore costs and tax.
 Illustrative annual-pay bond; three years remaining, no accrued interest, fees, taxes or payment failure. View full-size diagram
Yield to maturity brings the timeline into the calculation
Yield to maturity, or YTM, is the discount rate that equates the purchase price with the present value of the promised remaining cash flows. You do not need to memorise the formula to use the idea. It asks: what single annualised rate makes this price consistent with this payment schedule?
For the example above, the scheduled cash flows are ₹800 after one year, ₹800 after two years and ₹10,800 after three years. Solving for the annual rate gives approximately 10.01% at a ₹9,500 price, 8.00% at ₹10,000 and 6.13% at ₹10,500. These are mathematical illustrations, not available investment yields.
The price equation is:
Price = ₹800 ÷ (1 + y) + ₹800 ÷ (1 + y)² + ₹10,800 ÷ (1 + y)³, where y is the annual yield expressed as a decimal.
This is why the premium buyer’s YTM is lower than the 7.62% current yield. The current-yield figure does not recognise the ₹500 difference between purchase price and redemption. See the NSE’s bond explanation for the relationship between yield and the full set of payments.
A calculated yield is not a guaranteed outcome
The scheduled cash-flow calculation assumes the stated payments happen. If a payment is late, reduced or missing, the realised return changes. If you sell early, the sale price becomes part of your actual cash flows. Taxes and transaction costs can also change the result.
There is another distinction worth taking slowly. YTM is an internal rate of return on the assumed cash flows. To turn all interim coupons into a final accumulated sum growing at that same compound rate, you would have to reinvest those coupons at that rate. Spending the coupons or reinvesting them at a different rate gives a different terminal wealth outcome.
For example, our ₹10,000 bond at par has an 8% YTM under the assumptions. If you spend each coupon, you receive ₹2,400 of interest over three years and ₹10,000 principal at maturity. You do not also receive ₹10,000 × 1.08³ as a separate maturity payment. That larger accumulated figure would involve reinvesting the coupons at 8%.
Dates and conventions belong beside the number
Real calculations can involve half-yearly coupons, odd periods, accrued interest, settlement dates and different day-count conventions. Compare quoted yields on a consistent basis. A calculation using yesterday’s price is not necessarily the return implied by today’s executable order.
The NSE yield calculator asks for conventions and instrument inputs for a reason. Entering the wrong coupon frequency or redemption date can produce a precise-looking answer to the wrong question.
Where an issuer can call a bond, yield to call models payments to a specified call date at the specified call price. It does not establish that the call will happen. A platform may also show a yield-to-worst measure based on particular permitted scenarios. Ask which scenarios and conventions were used.
Read the claim as a complete sentence
When a yield catches your eye, add the missing words: calculated from which price, settled on which date, assuming which payments, before which costs and taxes, and ending when?
A reader who can ask those questions is much harder to mislead than a reader who has merely learned the term YTM.
The coupon belongs to the contract. Your return belongs to the price you pay and the cash flows you actually receive.
Try it yourself
Take our ₹800 annual coupon and a ₹10,200 purchase price. Current yield is about 7.84%. Would the three-year YTM be above or below that figure? It would be below it, because the assumed principal repayment is only ₹10,000. The exact answer requires the full timeline; the direction is already understandable.